
There is no single statewide deadline for filing a hail claim in Texas; your clock is set mostly by your own policy. Many carriers include a wind and hail notice clause, often one year from the storm date, and most policies also limit how long you have to sue. If spring 2026 hail hit your roof, check your policy’s “duties after loss” section now, not next spring.
This guide explains which deadlines can apply to a Texas hail claim as of October 2026, where to find them in your paperwork, what Texas Insurance Code Chapter 542A adds if a claim ends in a dispute, and how to document damage before time runs short. It is general information, not legal advice. If your claim is disputed or a deadline is close, talk to a Texas attorney or call the Texas Department of Insurance (TDI).
Why does the date of a spring hailstorm matter in October?
The storm date usually starts every clock in your policy. If your carrier uses a one-year wind and hail notice clause, a storm in April or May 2026 means notice could be due by April or May 2027. Hail damage is often invisible from the ground, so many homeowners only learn about it months later.
Texas sees a lot of hail. State Farm reported paying more than $5.6 billion in U.S. hail claims in 2025, with Texas leading at about $1.4 billion, up 27% from the year before, according to the State Farm newsroom. United Policyholders reports that Texas logged 902 major hail events in 2025 and led the nation in hail for the 11th straight year.
With that many storms, it is easy to lose track of which one damaged your roof. Insurers generally want a specific date of loss, so pinning down the right storm early makes the rest of the process smoother.
What deadlines can apply to a Texas hail claim?
Three kinds of time limits usually matter: the notice deadline in your policy, the policy’s limit on lawsuits, and the pre-suit notice required by Chapter 542A. Texas law also sets timelines your insurer must follow once you file. None of these replaces reading your own policy, because wording varies by carrier and endorsement.
| Time limit | Where it comes from | What to know (as of Oct 2026) |
|---|---|---|
| Notice of loss | Your policy | Often “prompt” notice; many carriers add a wind/hail clause, commonly one year from the storm. Check yours. |
| Suit limitation | Your policy, plus Civ. Prac. & Rem. Code §16.070 | Policies often say “two years and one day.” Texas generally bars contract limits shorter than two years. |
| Insurer response | Insurance Code Chapter 542 | Deadlines for the insurer to acknowledge, accept or reject, and pay a claim. |
| Pre-suit notice | Insurance Code Chapter 542A | Written notice at least 61 days before filing a weather-related lawsuit. |
The notice clause in your policy
Most homeowners policies require “prompt” notice of a loss. Many carriers go further with a specific wind and hail provision that sets a hard cutoff, often one year after the storm. Some policies are stricter or looser, and endorsements can change the base form. Do not assume your neighbor’s deadline is yours.
The limit on lawsuits
Policies usually include a “suit against us” clause limiting how long you have to sue the carrier. Texas Civil Practice and Remedies Code §16.070 generally voids contract terms that shorten a limitations period to less than two years. When that period starts can be a legal question, so ask an attorney if you are close.
The insurer’s own deadlines
Once you file, Insurance Code Chapter 542 (the prompt payment rules) requires insurers to acknowledge the claim, request information, decide, and pay on set timelines. The clock runs against the insurer only after you give notice. One more reason not to wait.
What does Chapter 542A add for hail claims?
Chapter 542A, sometimes called the “hailstorm bill,” took effect September 1, 2017. Before suing over a weather-related property claim, you must send written notice at least 61 days before filing. The notice must state the amount you claim is owed and your attorney’s fees. Skipping it can limit fee recovery.
According to a K&L Gates summary, the law covers first-party property claims arising wholly or partly from forces of nature, including hail, wind, tornadoes and hurricanes. If the notice is missing or the insurer is denied a reasonable inspection, a court may pause the case. Recovering much less than the amount demanded can also shrink or wipe out attorney fee awards.
The practical takeaway: if a claim ends in a dispute, you need about two months of runway before any lawsuit deadline. That is another reason to file early and keep good records.
How do I find my policy’s hail deadline?
Look at three places: the declarations page, the “duties after loss” or “conditions” section, and any endorsements listed on the declarations page. A wind and hail clause is often in an endorsement, not the main form. If you cannot find it, ask your agent or carrier in writing and save the reply.
- Declarations page: lists your deductibles and every endorsement attached to the policy.
- Duties after loss: explains notice, proof of loss and protecting the property from further damage.
- Endorsements: may add a wind/hail notice window, an actual cash value roof schedule or a cosmetic damage exclusion.
- Renewal packets: carriers sometimes change terms at renewal, so check the current policy, not the one you bought years ago.
Also check whether you have a cosmetic damage exclusion. TDI addressed a cosmetic damage exclusion endorsement for roof coverings in a 1998 bulletin. If your policy has one, dents that do not affect function may not be covered, which changes what is worth claiming.
What if I am not sure my roof was damaged in spring 2026?
Get a roof inspection before you decide. Hail bruising on shingles, dented vents and gutters, and granule loss can be hard to see from the yard. An inspection with dated photos tells you whether there is anything to claim, and public storm reports help match damage to a specific storm date.
Storm report aggregators that compile National Weather Service Storm Prediction Center data, such as HailDrive, can show which days hail was reported near your address. Treat these as a starting point. Your insurer will make its own determination.
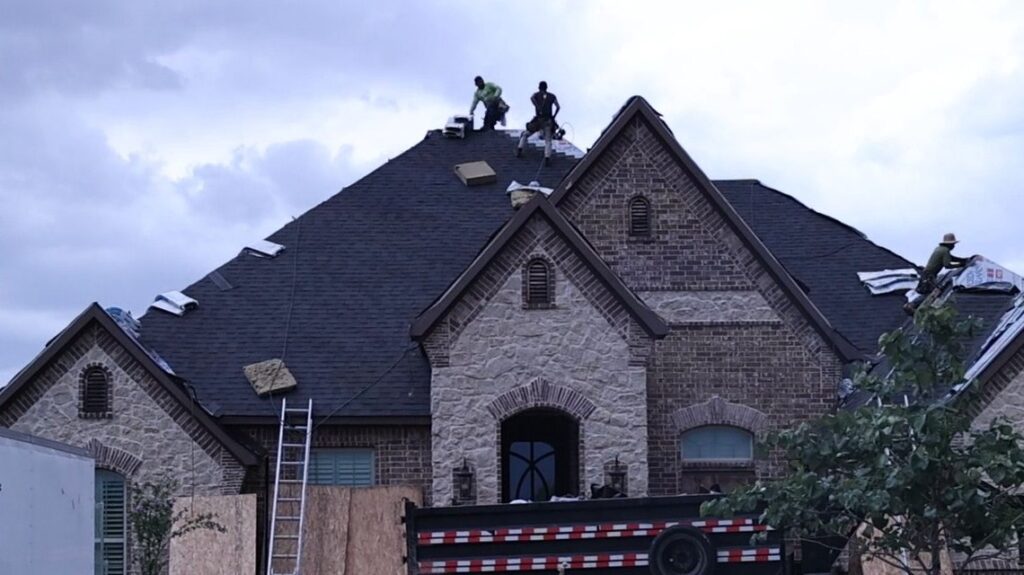
If you live in DFW, our team can inspect your roof, photograph what we find and give you a written summary. We document damage, and we can meet your adjuster on site to show what we found. You file and manage your own claim, and you deal directly with your insurer on coverage.
What should I document right now?
Write down the storm date, take dated photos of the roof, gutters, siding, windows and outdoor equipment, and keep receipts for any emergency repairs. Your policy likely requires you to protect the property from further damage, so a tarp over an active leak is usually expected, not optional.
- Date of loss: note the storm date and any local news or storm reports that confirm hail at your address.
- Photos and video: wide shots and close-ups, including soft metals like vents and gutters, which often show hail dents clearly.
- Interior damage: water stains on ceilings or in the attic, with dates.
- Mitigation receipts: tarps, board-ups and any emergency work.
- Communication log: claim number, adjuster name, dates of calls and copies of emails.
Can a roofer file my hail claim for me?
No. In Texas, a contractor who works on your property cannot act as your public adjuster or advertise that they will handle your claim, under Insurance Code §4102.163. A roofer also cannot waive, rebate or absorb your deductible under Business and Commerce Code §27.02. You file the claim and pay your deductible.
TDI lays out these rules on its Roofing and insurance: know the law page. Contracts of $1,000 or more that involve an insurance settlement must include a notice that you are required to pay your deductible. If a contractor offers to “cover” your deductible or negotiate your settlement, that is a red flag. You can report it to the Texas Attorney General at 800-621-0508.
A good roofer’s role is narrower and more useful: find the damage, document it clearly, explain the repair or roof replacement options, and do the work well once you and your insurer have settled the claim.
Should I replace or repair once the claim is approved?
That depends on the extent of damage, the roof’s age and what your insurer approves. If you are replacing, ask about impact-resistant (UL 2218 Class 4) shingles. Many Texas insurers offer discounts for impact-resistant roofs, and the amount is set by each insurer. The roofer signs TDI form PC068 to certify the install.
See TDI’s roofing discount page and the PC068 installation form. Ask your agent what credit your carrier gives before you choose materials. If you are also thinking about panels, a reroof is a natural time to plan solar so you are not removing and reinstalling an array later.
If spring hail may have reached your roof and you are in the Dallas-Fort Worth area, we are happy to take a look and give you a clear, documented answer. Reach out to our Fort Worth team to schedule an inspection while your policy’s clock still has room.
Prometheus Power Solutions · Fort Worth, TX
Storm damage or an aging roof?
Get a straight answer from a local Fort Worth roofing team: what we find, what it should cost and what your options are.
Book a Free ConsultationCall 817-523-9029
★★★★★ 5.0 on Google · Serving all of Dallas–Fort Worth
Frequently Asked Questions
How long do I have to file a hail claim in Texas?
It depends on your policy. Texas has no single statewide filing deadline for homeowners. Many carriers use a wind and hail notice clause, often one year from the storm date, so check the duties after loss section and endorsements in your current policy.
What is the 61-day notice rule for Texas hail claims?
Texas Insurance Code Chapter 542A requires written notice at least 61 days before filing a lawsuit over a weather-related property claim. The notice must state the amount claimed and attorney fees. It applies to lawsuits, not to filing the claim itself.
Can I still file a claim for hail from spring 2026?
Possibly. If your policy uses a one-year wind and hail notice window, a spring 2026 storm could still be claimable into spring 2027. Confirm your exact deadline with your agent or carrier in writing, and get a documented roof inspection soon.
Will a DFW roofer handle my insurance claim?
A Texas roofer cannot act as your public adjuster or waive your deductible. You file and manage the claim. A roofer can inspect, document damage with photos, and meet your adjuster on site to show what was found.